Healthcare Workers Face Rising Insurance Costs, Affecting Financial Choices
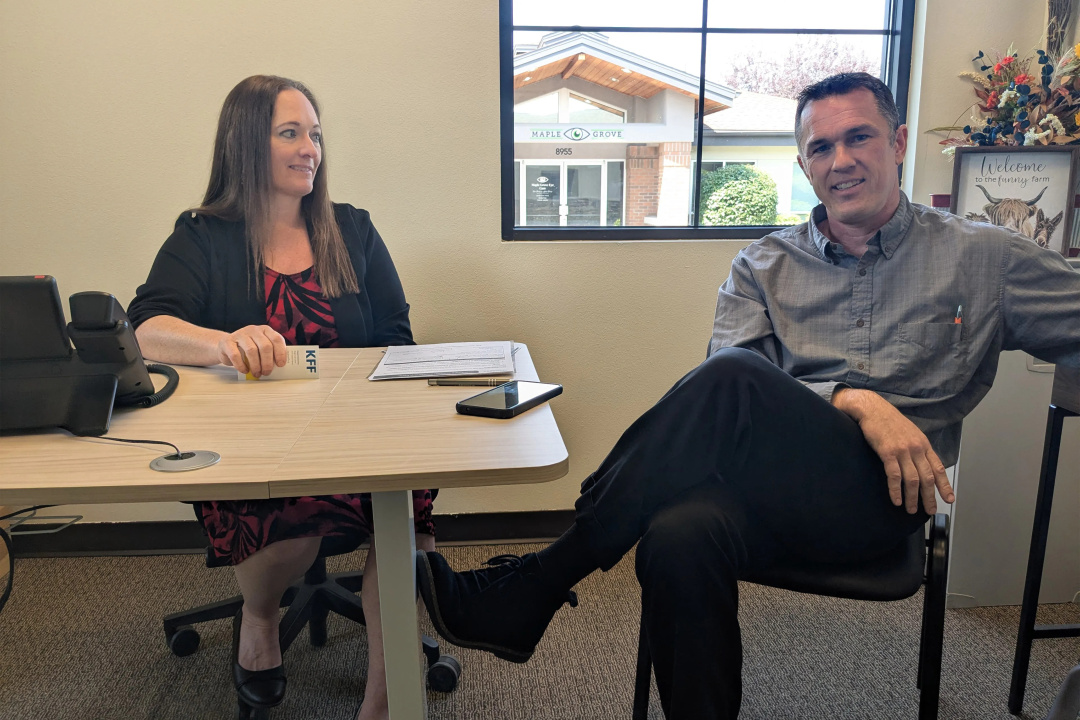
In Boise, Idaho, Joshua and Ashley Durham, who operate a family medicine practice, have made the unprecedented decision to forgo health insurance. For the first time in their lives, they are navigating the complexities of healthcare without coverage, a choice driven by soaring premiums. After starting their practice in late 2023, they initially secured insurance through the Affordable Care Act marketplace. However, they found that their monthly premiums surged to nearly $1,600 this year, prompting them to rely on their health savings account to cover medical expenses instead.
Joshua Durham, 47, expressed the anxiety that accompanies their decision, noting, "It’s nerve-racking. It just takes, you know, one little accident, and then you got a big fat bill." This sentiment is echoed across the healthcare sector, where traditionally, a higher percentage of workers are insured compared to the general population. In 2024, 7% of healthcare workers were uninsured, compared to 11% of all adults under 65, according to a KFF analysis.
The rising costs of health insurance are not just a personal issue for the Durhams; they reflect a troubling trend impacting many in the healthcare field. Employers are bracing for an anticipated 8.2% increase in health insurance costs for 2027. The decision by the Republican-led Congress not to renew Affordable Care Act marketplace credits, which had provided financial relief during the COVID-19 pandemic, has further exacerbated the situation. While low-income subsidies remain, the absence of pandemic-era credits has left many, particularly those in small businesses like independent medical practices, struggling to afford coverage.
Jack Dillon, executive director of the Association for Independent Medicine, highlighted the untenable nature of these premium increases for small practices, stating, "The cost has become so astronomical. You’re looking at it and saying, ‘What’s the value?’" As healthcare becomes less affordable, some employers may resort to offering higher wages or minimal insurance plans to cope with the financial strain.
The Congressional Budget Office predicts that the number of uninsured individuals in the U.S. could rise by approximately 15 million over the next decade due to the expiration of expanded ACA subsidies. This trend is concerning as healthier individuals may opt out of insurance, leaving a higher proportion of sicker patients in the insurance pool, which in turn drives up costs.
Samantha LeGault, a nurse practitioner, shared her own struggles with rising premiums, which jumped from $700 to $1,500 monthly. With chronic health issues in her family, she feels compelled to maintain coverage despite the financial burden. LeGault has had to make difficult choices, such as prioritizing her children's dental care over her own and switching her children to public school to manage costs.
The Durhams also employ three staff members, two of whom receive insurance through their spouses. They contribute $420 monthly toward their physician assistant’s premiums. Joshua Durham, while knowledgeable about medical care, acknowledges the ethical dilemmas of treating himself and his family, which the American Medical Association generally discourages.
Arthur Caplan, a bioethicist, suggests that as more individuals turn to family members for care due to accessibility issues, it may be time to reevaluate the ethical guidelines surrounding self-treatment.
The financial strain of healthcare is a universal concern, as illustrated by Jill Kordick, a retired healthcare executive, who opted for insurance despite the costs. After losing enhanced ACA tax credits, her premiums rose to $800 monthly, leading her to delay necessary medical care due to high deductibles. Kordick's experience underscores the fragmented nature of the healthcare system, which affects both patients and providers.
The Durhams are acutely aware of how unaffordable healthcare impacts their patients. They strive to provide some flexibility in payment options when possible, reflecting their commitment to patient care despite their own financial challenges. Joshua Durham's childhood experiences with medical debt have left him wary of their uninsured status, as he recalls the struggles his family faced.
As they navigate this challenging landscape, the couple has spent around $9,000 from their health savings account this year, covering various medical expenses, which, while significant, still falls short of the cost of traditional insurance premiums. For now, their decision to go uninsured has been manageable, but the uncertainty of future healthcare needs looms large.